In a more volatile world, capital growth has ceased to be investors’ top priority, according to Schroders Global Investor Insights Survey 2026. Instead, equities must play a part in achieving greater diversification and downside protection.
Global investors are recalibrating what they want from equities and their investment portfolios overall. Long-term capital growth may still be one requirement, but it is no longer the top priority, according to the latest Schroders Global Investor Insights Survey (GIIS) 2026.
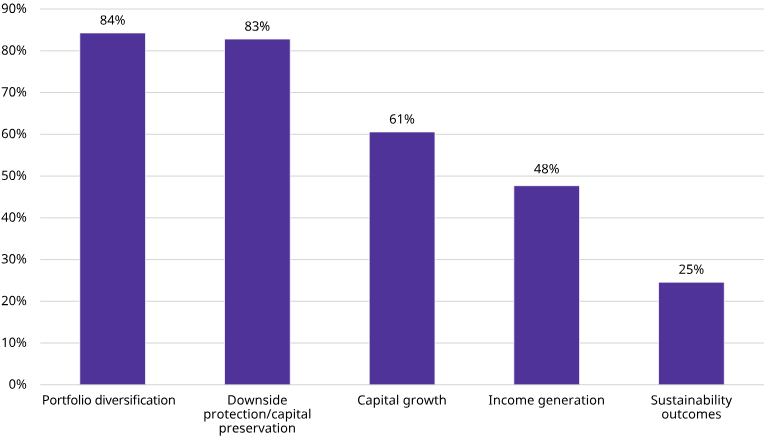
The survey, which questioned over 1,000 professional investors from 24 countries, found that most respondents (85%) expect higher volatility over the coming year. Ranking their top portfolio objectives in the current macro environment, portfolio diversification (84%) and downside protection/capital preservation (83%) top the list, ahead of the need for capital growth (61%).
Figure 1. What are your primary portfolio objectives in the current environment?
That helps explain why active management is front and centre of investors’ minds. An overwhelming 85% of respondents say they are confident active management can help them achieve their investment objectives over the next 12 to 18 months.
When asked where they see the greatest portfolio benefit from increasing their active management allocation, the top three asset classes cited are global equities (37%), small/mid-cap equities (32%) and real assets (28%). This points to a more outcome-oriented approach to an equities allocation, one that prioritises resilience and diversification alongside long-term growth.
Johanna Kyrklund, Group Chief Investment Officer at Schroders, said:
“In recent years we have moved from a globalised world prone to deflationary shocks to a geopolitically fragmented world, where restructuring of supply-chain can contribute to inflationary shocks.
“The ability to be selective, manage risk and respond dynamically to fast-moving market conditions is our active edge to navigating these choppier waters.”
Diversification away from the US: the opportunity set is widening
When it comes to the increased need for diversification, a key finding from GIIS 2026 is the growing emphasis on finding opportunities outside the concentrated US stock market and seeking more varied sources of return. This reflects wider concerns that recent equity gains have been driven by a narrow group of AI-exposed mega-cap technology stocks.
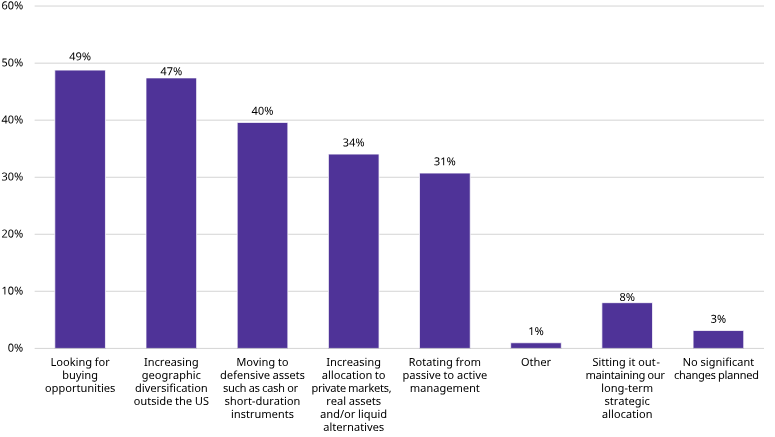
When asked about upcoming portfolio changes, respondents ranked “looking for buying opportunities” (49%) and “diversifying away from the US” (47%) as their top choices, indicating that global equities are increasingly being used as an active allocation lever, widening the opportunity set beyond the dominant areas of recent market performance. This suggests that in a more volatile environment, geographic diversification is a practical tool for building resilience.
Figure 2. Which of the following portfolio changes are you making or planning to make?
Equities linked to portfolio priorities and to opportunity-seeking
GIIS 2026 also suggests that investors are becoming less constrained by the structure of equity exposure itself. Portfolio objectives are increasingly taking precedence over structural distinctions between asset classes, including whether exposures are public or private. Rather than treating the opportunity set as separate silos, many investors are applying a combined framework that considers equity opportunities across both public and private markets, focusing on outcomes (such as growth, income and inflation protection).
Important information
Marketing material for financial professionals only.
All investments involve risk, including loss of principal.
The views and opinions contained herein are those of Schroders and may not necessarily represent views expressed or reflected in other Schroders communications, strategies or funds. Such opinions are subject to change without notice. The material is not intended as an offer or solicitation for the purchase or sale of any financial instrument(s). The material is not intended to provide, and should not be relied on for, accounting, legal or tax advice, or investment recommendations.
Any reference to regions/ countries/ sectors/ stocks/ securities is for illustrative purposes only and not a recommendation to buy or sell any financial instruments or adopt a specific investment strategy. Past performance is not a guide to future performance and may not be repeated. The value of investments and the income from them may go down as well as up and investors may not get back the amount originally invested. Diversification cannot ensure profits or protect against loss of principal.
This document may contain “forward-looking” information, such as forecasts or projections. Please note that any such information is not a guarantee of any future performance and there is no assurance that any forecast or projection will be realized.
Schroder Investment Management North America Inc., 7 Bryant Park, New York NY 10018-3706. CRD Number 105820. Registered as an investment adviser with the US Securities and Exchange Commission.